

CashBook - Balance & Expense
by Obopay – Payment Wallet for Businesses
3.8
- Safety
- 100% Safe
- Category
- Business
- Ratings
- 3.8
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
Managing everyday money is often less about complicated accounting and more about being able to record things clearly when life is busy. CashBook - Balance & Expense is a business app from Obopay – Payment Wallet for Businesses that focuses on that practical gap: keeping track of cash flow, daily balance, income, and expenses in one place. I see it as a straightforward cash-book companion rather than a full accounting suite, and that distinction matters when deciding whether it fits your routine.
I spent time looking at how the app works as a tool for small businesses, independent workers, household budgeting, and anyone who still handles a meaningful amount of cash. Its free download and Everyone age rating make it easy to approach, while the current version, 8.7.3, supports devices running Android 7.0 or later. The app has reached over 5 million installs and holds an average rating of 3.8 from around 207 thousand ratings, so it is clearly familiar to a large audience, though the middling score also suggests that the experience will not suit every user equally.
How clearly the app presents money information
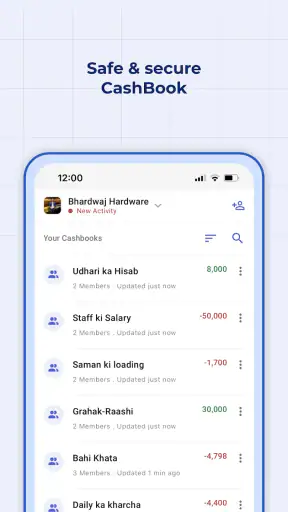
The strongest part of CashBook is its narrow purpose. Instead of asking me to learn formal bookkeeping language, it centers the daily questions most people actually have: how much came in, how much went out, and what should the balance be now? That focus can make the first few sessions less intimidating than opening a traditional accounting application filled with ledgers, tax terminology, invoices, and reports.
For a shop owner, the useful habit is to record a transaction close to the moment it happens. A cash sale, supplier payment, delivery cost, or small withdrawal can otherwise disappear from memory by the end of the day. CashBook gives those events a dedicated home, which is more dependable than scattered notes, messaging yourself, or trying to reconstruct everything from a wallet at night.
I also like the idea of separating income and expense entries instead of treating the balance as a single number with no explanation. A balance tells me what remains, but the movement behind it tells me whether the business is healthy, whether a particular cost is growing, or whether I simply forgot to record something. That distinction is valuable for self-employed users who need a quick financial picture without wanting to maintain a complex spreadsheet.
Navigation is most comfortable when I already know what I want to do: add money received, enter a cost, or check the running position. The app’s business-first identity helps keep those actions relevant. It is less likely to distract me with unrelated financial products than a banking app, and less demanding than accounting software designed around formal reporting.
That simplicity has a trade-off. Users who expect polished dashboards, advanced categorization, automated bank imports, payroll tools, inventory management, or professional tax reports may find the experience limited. CashBook is best understood as a record-keeping layer. It can help me maintain discipline, but it does not replace the broader financial systems that a growing company may eventually need.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Readability matters more than decoration
For financial records, readability is not just a visual preference. I need to distinguish an incoming amount from an outgoing amount quickly, especially when reviewing several entries after a busy workday. A clean list and clear labels are more useful here than decorative graphics or a crowded dashboard. The app’s focused scope gives it a reasonable foundation for that kind of scanning.
My practical advice is to establish a consistent entry style from the beginning. Use familiar descriptions, avoid abbreviations that only make sense today, and record the purpose of a payment rather than relying on memory. This is an important accessibility-minded habit because clear wording reduces the mental effort required later, whether the user is tired, distracted, or asking someone else to review the records.
People with reading difficulties may benefit from short, predictable labels and a routine that limits each entry to the information they genuinely need. At the same time, I would not assume that a simple layout automatically works for every reader. Text size, contrast, spacing, and the visual distinction between financial states can affect whether someone can use the app comfortably. Anyone who depends on enlarged text or a screen reader should test the current build on their own device before moving all financial records into it.
Reducing mental load during a busy day
A small business cash book becomes much easier to use when it is treated as a series of tiny actions rather than one large bookkeeping task. I would enter a transaction immediately, check the daily balance at a natural pause, and do a short review before closing for the day. This workflow avoids the exhausting end-of-week reconstruction that causes many records to become incomplete.
Here is a realistic example. Imagine I run a small food stall. During the morning I receive cash from customers, then pay for packaging and ingredients. Instead of keeping receipts in a pocket and guessing at the evening total, I record each movement as it happens. At closing time, I compare the app’s balance with the physical cash. If the figures differ, I can investigate while the details are still fresh. That is a modest workflow, but it is more useful than a sophisticated report I never maintain.
For users with attention-related difficulties, the same approach can be adapted into a fixed sequence: record income, record expenses, check the balance, then stop. The important insight is that consistency matters more than entering every possible detail. Overloading each transaction with unnecessary notes can make the process feel like paperwork and increase the chance that entries are skipped.
Using CashBook across different abilities and situations
I find that the best way to judge a cash-book app is to ask whether it still feels manageable on an ordinary, tiring day—not just when I’m first exploring it. In this section, I’m looking at how different working conditions and abilities can shape that experience, and why a small adjustment to the routine may matter as much as the app itself.
Motor considerations and one-handed use
Money apps are often used while standing behind a counter, carrying stock, or moving between customers. That makes one-handed operation and forgiving input especially important. CashBook’s value is highest when an entry can be made without turning a simple payment into a long administrative session. I would keep the phone in a stable place, use a repeatable routine, and avoid waiting until the end of a crowded shift to enter everything.
Users with limited dexterity should pay attention to how comfortably they can select fields, enter amounts, and correct mistakes. A compact phone screen can make small controls harder to activate accurately, while fatigue can turn repeated tapping into a genuine barrier. The app may still work well for someone who enters only a few transactions at a time, but a person recording dozens of movements daily should test the physical effort before committing to it.
One useful trade-off is accuracy versus speed. Rushing an amount entry saves a moment but can create a much larger problem during reconciliation. I would rather pause briefly to verify the number and transaction type than build a fast routine around corrections. This is especially important for users who experience tremors, reduced fine-motor control, or difficulty maintaining focus while entering digits.
A stylus, a larger-screen Android device, or a quiet recording station may make the experience easier, although those are workflow choices rather than features I would attribute to the app itself. If another person helps with bookkeeping, agreeing on a single entry method can also prevent inconsistent descriptions and duplicate records.
Sensory and cognitive context
CashBook is potentially useful for people who prefer concrete, task-based financial tools. The central concepts—income, expense, and balance—are easier to understand than a full accounting vocabulary. That can help a first-time business owner, an older user learning digital record keeping, or someone who becomes overwhelmed by too many financial categories.
However, simplicity should not be confused with universal ease. A user with low vision may need larger system text or a different display environment. A user with color-vision differences should not have to rely on color alone to understand whether money was added or spent; the labels and amounts need to make that distinction clear. Someone with dyscalculia may need a second checking method, such as comparing the recorded balance with physical cash or a written daily total.
For users who are deaf or hard of hearing, visual information is naturally more important than sound-based cues. For users who cannot comfortably look at a phone in a noisy shop, the challenge is different: entering records later may be more realistic than trying to use the screen during a transaction. In that case, I would keep receipts or a temporary written tally, then transfer the information during a quiet break. The app can support the final record, but it cannot remove the environmental problem.
Language and literacy also influence access. Financial entries should be written in words the whole team understands, particularly if more than one person handles the cash book. A plain description such as “market supplies” is more useful later than a private abbreviation. This is one of the simplest ways to make a shared record more inclusive without adding complexity.
Situational access for real working conditions
The app makes the most sense for people who need a portable cash record rather than a permanent desk-based accounting system. A market seller, mobile service provider, freelancer, community group, or small family business can check the day’s position from an Android phone instead of carrying a notebook everywhere. That portability is helpful when the work location changes or when internet-dependent tools are inconvenient, though I would still plan how records are protected and backed up in my own routine.
It is also a reasonable option for someone transitioning from paper. I would not attempt to digitize years of old notes in one exhausting session. A better approach is to choose a clear starting point, enter the opening balance carefully, and use the app consistently from that day onward. This avoids mixing incomplete historical information with new entries and gives the user a clean way to judge whether the routine is working.
Compared with a spreadsheet, CashBook is more approachable for someone who does not want to design formulas or maintain columns. A spreadsheet remains better for custom analysis, shared editing, detailed categories, and calculations that go beyond a simple cash book. Compared with a banking app, CashBook is more suitable for recording cash transactions and business movements that may never appear automatically in a bank feed. A banking app is stronger for confirmed account activity, transfers, and formal statements.
Compared with full accounting software, this app is lighter and likely easier to start, but it gives up depth. Accounting platforms are the better choice when I need invoices, tax preparation, inventory, multiple accounts, staff permissions, or structured financial reporting. Choosing CashBook makes sense when the priority is a dependable daily record, not a complete back office.
Costs, expectations, and practical boundaries
The app is free to download, which lowers the barrier for a new user who wants to test a digital cash book before paying for a larger system. It also includes in-app purchases ranging from around $2.49 to around $549.99 per item. That is a very wide range, so I would review any purchase screen carefully and decide what the free experience already covers before spending money. A small trial for a simple operation is a different decision from adopting a paid tier for a larger business.
The Everyone rating makes the app broadly approachable from an age perspective, but age suitability does not guarantee that the financial workflow will be appropriate for a child or inexperienced user. A young person helping with a family business may still need supervision around entries, balances, and purchases. Likewise, a free app can be useful without being the right place for sensitive, high-volume business accounting.
The developer name, Obopay – Payment Wallet for Businesses, may lead some people to expect payment-wallet functions rather than primarily cash-book organization. I would therefore approach it by testing the record-keeping workflow first: can I add the kinds of income and expenses I actually handle, review them comfortably, and reconcile the balance without confusion? That practical test is more important than assuming the name means it will replace a bank or payment terminal.
Remaining barriers before making it your main record
The biggest barrier is not necessarily a missing button; it is the responsibility of maintaining accurate records. Any manual cash-book app depends on the user entering information correctly and consistently. If several people take money from the same drawer but only one person records transactions, gaps are likely. A short daily review and a clear handover routine can reduce that risk.
Another barrier is scale. A business with many transactions, several employees, multiple locations, or formal compliance obligations may quickly outgrow a simple cash-flow tracker. In that situation, CashBook could still serve as a quick field note, but I would not rely on it as the only financial system without checking whether its records meet the organization’s needs.
Accessibility testing should also be personal rather than assumed. Before entering important data, I would check the app with the phone settings I normally use, including larger text, a preferred display mode, and any assistive tools I depend on. I would try creating, editing, and reviewing an entry, not just opening the first screen. The most important barrier may appear during correction or reconciliation rather than during initial setup.
Privacy and continuity deserve the same practical attention. I would avoid treating the phone as the sole copy of essential financial information. Regularly preserving important totals through a separate, secure method is sensible for any manual record system. I would also keep the app updated when appropriate, while remembering that an update can change the layout or workflow and may require a quick accessibility check afterward.
Finally, users should be realistic about what the app can prove. A recorded expense is not automatically a receipt, an official statement, or a tax document. If a lender, accountant, partner, or authority needs formal evidence, I would retain the relevant supporting documents and use a more suitable accounting process alongside the cash book.
My inclusive verdict
I recommend CashBook to someone who wants a focused way to record daily income, expenses, and cash balance without starting with a complicated accounting package. Its clearest strength is the direct connection between everyday transactions and the question of how much money remains. For a solo worker or small cash-based operation, that can be enough to create a useful financial habit.
I would recommend it especially to users moving away from paper, people who prefer short task-based workflows, and owners who need a portable record while working away from a desk. The best results come from entering transactions promptly, using consistent descriptions, checking the physical or known balance regularly, and keeping a separate safety copy of important information.
I would choose a spreadsheet instead when customization and analysis matter most. I would choose full accounting software when the business needs invoices, tax workflows, inventory, staff access, or formal reports. I would choose a banking app for verified account activity rather than manually recorded cash movements. CashBook sits between a notebook and a complete accounting system, and it is most successful when I accept that middle ground.
My final view is positive but measured. The app’s focused design can make money tracking less intimidating and more manageable, yet manual entry, screen comfort, transaction volume, and individual accessibility needs still determine whether it works well. With its free starting point, broad age rating, Android compatibility from version 7.0 onward, and substantial user base, it is worth testing for a small operation. The right question is not whether it does everything, but whether it makes your daily cash routine clearer and easier to maintain.
For me, that is the meaningful test. If I can record a payment without friction, understand the day’s movement at a glance, and reconcile the result before small errors become large ones, the app is doing its job. If I need automation, deep reporting, or a highly customized accessible workflow, I would move to another tool rather than forcing this one beyond its intended role. CashBook is a practical starting point for inclusive everyday bookkeeping, provided the user checks its interface personally and keeps expectations grounded.
Pros
- Quickly records income and expenses with minimal effort.
- Clear balance overview helps track daily financial health.
- Supports multiple accounts for separating cash and bank funds.
- Useful charts make spending patterns easier to understand.
- Works well for simple personal budgeting and expense tracking.
Cons
- Advanced budgeting tools may be limited for complex financial planning.
- Manual entry can become tedious when recording many transactions.
- May require time to customize categories to match your spending habits.
- Users should verify backup options before switching or resetting devices.
- Currency and regional features may not cover every country equally.
FAQs for CashBook - Balance & Expense
What is CashBook - Balance & Expense used for?
CashBook - Balance & Expense is designed to help you record and organize everyday financial activity in one place. You can add income, expenses, transfers, and other transactions, then review your balance and spending history. It is useful for personal budgeting, household money management, or simply keeping a clearer record of where your cash goes.
Is CashBook - Balance & Expense suitable for beginners?
Yes. The app is generally easy to understand because its main purpose is straightforward: enter your transactions and monitor the results. New users can begin with a few basic categories, such as food, transport, bills, and salary, without creating a complicated budget. As your records grow, you can use its summaries and reports to identify spending patterns more confidently.
Can I use CashBook - Balance & Expense to manage multiple accounts or wallets?
CashBook - Balance & Expense can be useful when you separate money into different sources, such as cash, a bank account, a card, or a savings wallet, depending on the features available in the installed version. This makes it easier to understand where your money is held and how it moves. Before relying on it for detailed account management, check the current app listing for supported account options.
Does CashBook - Balance & Expense connect directly to my bank account?
You should not assume that the app automatically connects to every bank or imports transactions without setup. Many expense trackers rely on manual entry, while some versions or platforms may offer additional backup, import, or synchronization features. Review the permissions and feature description before downloading, especially if you prefer automatic bank updates or have concerns about sharing financial information.
Is my financial information safe in CashBook - Balance & Expense?
Because you may enter sensitive information such as balances, income, and spending details, privacy should be considered before using any finance app. Avoid recording unnecessary personal data, use device security features, and review the developer’s privacy policy and requested permissions. Also check whether backup, cloud synchronization, export, or passcode protection is available in the current Android or iOS version.

CashBook - Balance & Expense
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@cashbook.in, visit https://cashbook.in/, or review their https://cashbook.in/legal/privacy/.










